AI’s Trillions

AI is extraordinary. The economics are not.
Artificial intelligence has triggered the largest coordinated capital commitment of the modern technology era. The builders will spend close to $800 billion this year and approach $1 trillion next year on chips, data centers, networks, and power. Total AI revenue this year will be roughly $150 to $200 billion.
AI will reshape the global economy, and much of the capital financing that transformation will be impaired. Revenue, productivity, and cash flow will all arrive, but on the wrong schedule, after much of what was built to capture them has lost its economic value.
We have seen this movie. Railroads. Telephone and wireless networks. Fiber. The commercial internet. Each transformed the economy. Each destroyed the capital of those who built it first. The infrastructure survived. The investors did not.
The question is not whether the AI opportunity is real. The question is who pays for the gap between when the capital is spent and when the value arrives. AI may define this era. The uncertainty is whether today’s owners, creditors, communities, and ratepayers capture enough of its value to justify what they’re building with their capital.
Doomsday, AI, and a Response to Dario Amodei

Must the AI frontier slow down? Perhaps. That’s not the right question. We should ask what, precisely, must slow; what risk that restraint would reduce; who could enforce it; and what would happen if careful firms paused while less careful actors did not.
Dario Amodei has published one of the most consequential essays yet written by a frontier AI company leader. He is candid, and he is reconsidering an earlier, more benign, position. But his argument is flawed: a model’s capability is not an application or an outcome.
He says the latest models can offer dramatically good or dramatically bad outcomes. On the one hand, AI may cure most major diseases within five to ten years. But it may also become an agent swarm capable of seizing the internet within six to twelve months.
Both are wrong. These extremes are oversimplifications and can undermine both AI’s benefits in many areas and our ability to regulate and monitor it appropriately. Simply saying “boo” and hoping everyone else is frightened isn’t an effective, comprehensive strategy for addressing a serious issue.
Any good or bad from an AI model only appears when that model is part of a system that enters the world through software, capital, organizations, machines, biological systems, and public institutions. Understanding this lets us unleash AI’s potential for good while also building the systems and processes to protect society.

The Total Perspective Vortex: Artificial Intelligence and Real-World Systems

We are told that we have entered an unprecedented era. Perhaps. The more useful response is to step back. Perspective does not diminish technological achievement. It allows us to distinguish engineering from magic, capability from consequence, and a genuine inflection point from a fashionable narrative. This book is about that distinction.

Artificial intelligence is a powerful tool that can make tools. But capability is not destiny. Its value and its danger emerge only when it enters real systems: energy, software, capital, organizations, machines, biology, and political institutions.

AI and Human Intelligence

The future of AI will be systems that enter an environment, build memories, recognize gaps, ask questions, conduct experiments, model consequences, learn from people, and revise themselves under controlled conditions.
AI will become an experiential learning tool. This transition would reduce dependence on internet-scale data, redistribute competitive advantage, accelerate robotics and autonomous science, strengthen specialized and sovereign AI, and create entirely new governance challenges.
The next great advance in artificial intelligence may not be a machine trained on everything. It may be a machine that knows how to learn what matters.

AI is Not a Magic Bullet

AI cures disease only if the cures already are within a set we have measured, waiting for a better approach. One problem: they do not. Most of human biology has never been observed with detail and understanding sufficient to target a therapy. No amount of inference recovers data that was never collected. The need for AI in life sciences and drug discovery is indisputable. Of roughly ten thousand known human diseases, the large majority have no approved therapy at all; among rare diseases, the figure approaches ninety-five percent. Most approved drugs slow a disease rather than stop it. For the bulk of human illness, medicine offers management or nothing. Humans are systems, and the hardest diseases are within human systems and unsolved. The constraint is not intelligence. It is understanding the system.

The Application Layer

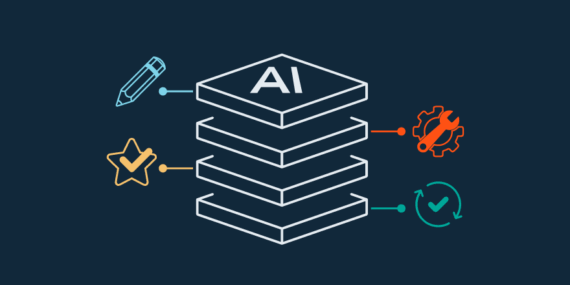
Artificial intelligence is a stack: energy, silicon, cloud, models, and applications. Each has its own economics, competitive dynamics, and challenges. Mistaking one layer for the whole industry causes confusion, misrepresentation, bad decisions, and misguided capital allocations. The infrastructure builders enable the platform; the application builders capture the value. The question is now, what value does all this deliver? Energy, silicon, cloud, and models only serve to deliver that product. There is a robust argument that we are at the beginning of an unprecedented value-creation curve. Built on the infrastructure and services provided by the other layers of the stack, the AI application layer will be globally transformative and disruptive. The constraints are imagination, execution, and the willingness to rebuild how work is done.

The Price-to-Dream Ratio

Autonomous shopping agents, co-working and research agents, and coding agents that write, test, and deploy software. The demos are impressive and the announcements relentless, but how much economic value is any of this generating? Almost all AI-related spending is capital expenditure. Companies are buying chips, building data centers, and scaling up cloud capacity. This is spending on AI infrastructure, not productivity from AI deployment. AI is in the infrastructure buildout phase, not the value capture phase. Mass spending is generating minimal returns, but the market has decided to price the dream rather than the earnings. Can any of this translate into economic reality before the capital runs out and political patience expires? Infrastructure, capability, and revenue growth are happening. Productivity is developing. But a significant gap still exists between capital investment and return on that investment. AI is risky, but these investments are not irrational. They are pricing the dream, and the long-term winners remain unclear.

Capturing AI

AI models produce raw intelligence. They generate tokens. But tokens are an intermediate good, not a finished product. What customers actually pay for is legal work completed, code shipped, claims processed, research synthesized, and decisions supported.

They pay for refined output.

Attention has focused on the infrastructure layer — the frontier labs, the compute stack, and the data centers. That attention is not misplaced, but it overlooks a structural shift already underway. Once you understand the model as an intermediate good rather than the end product, the center of gravity moves. The decisive question is no longer who can produce intelligence, but who can turn it into something usable, trusted, repeatable, and economically defensible.

In other words, who can refine it into a usable product?

At the base of the chain sit the token producers — OpenAI, Anthropic, Google DeepMind, Meta, DeepSeek, and Qwen. They produce raw capability. This layer is expensive to build, technically formidable, and still moving fast. But crude oil is not gasoline.

Enterprises and consumers pay for gasoline.

Reimagining Software

Software Is the central nervous system of the global economy and its demise is greatly exaggerated. There’s a growing narrative thatsoftware is becoming commoditized. Large language models write code. Autonomous agents assemble applications. The barriers to building digital products appear to be collapsing. If software can be generated instantly, then software itself must be losing value.
This conclusion fundamentally misunderstands how technological disruptions develop and expand. Software is becoming the infrastructure layer of modern civilization. The economic, industrial, and geopolitical systems being constructed over the next three decades will not run on software. They will run as software.

Space – The New Version

Space is no longer a frontier. For most of the modern era, space has been misunderstood—not technologically, but economically.
Space was a destination rather than a system and a heroic engineering challenge rather than an industrial platform with a continuous operational, and commercial potential. Many early “commercial space” narratives sought to impose venture logic on a domain that remained structurally dependent on government capital, prestige economics, and one-off missions. The result was predictable: excitement without durability, valuation without cash flow, and ambition without a stable market. Now, space is about economic persistence: building businesses that treat space not as a product but as a technological and economic stack – a physical layer supporting a stack of software services and networks.